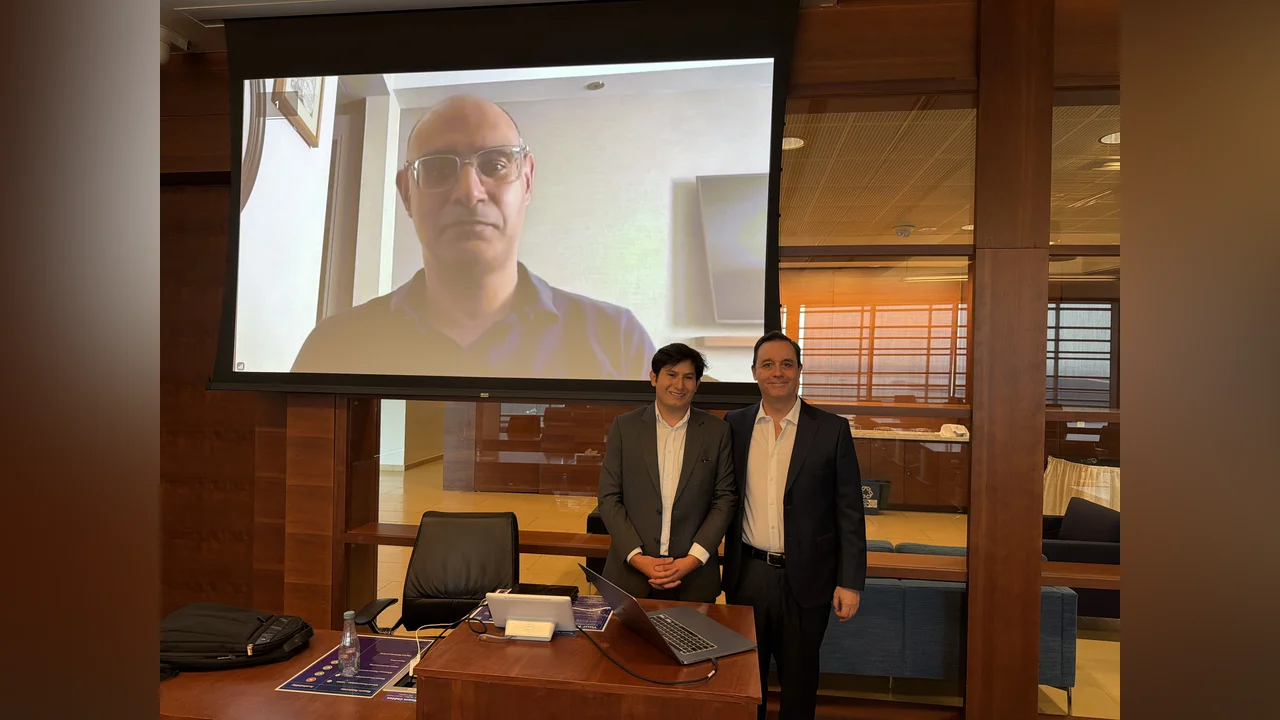
Miguel Alvarez successfully defends his PhD Thesis
Miguel Alvarez successfully defended his PhD Thesis entitled "Unbiased and Multilevel Monte Carlo Methods for Parameter Inference in Latent Stochastic Systems" on Octrober 14th, 2026.
About
Abstract:
In this document, we study score-based parameter inference for stochastic systems, primarily Hidden Markov Models (HMMs); we also consider the related problem of Conditional Stochastic Optimization (CSO). The score function is usually intractable, and time discretization is necessary to compute estimates of it; these estimates are computed using Sequential Monte Carlo (SMC) methods, which provide consistent estimators for nonlinear systems. Hierarchical methods such as Multilevel Monte Carlo (MLMC), together with unbiased methods, are used to jointly control the statistical error introduced by SMC and the bias introduced by time-discretization, thereby improving the efficiency of the computations. A similar treatment is given to the CSO problem, where we relate the nested randomness of the problem to unbiased estimators and Markovian Stochastic Approximation (MSA).
First, we study filtering and online parameter estimation for a partially observed diffusion whose observation times follow a Cox process depending on the diffusion. We develop a multilevel particle filter and an unbiased particle filter that allow the drift, observation density, and observation times to depend on the unknown parameters. For an MSE of $\mathcal{O}(\epsilon^2)$, our multilevel estimator costs $\mathcal{O}(\epsilon^{-2.5})$, against $\mathcal{O}(\epsilon^{-3})$ for an ordinary particle filter, while the unbiased variant removes the time-discretization bias entirely.
Second, we consider parameter estimation for partially observed diffusions whose diffusion coefficient itself depends on the unknown parameter, a case existing score-based methods cannot handle. Using a continuous-time, bridge-based backward-sampling particle filter combined with a double-randomization stochastic approximation scheme, we obtain a parameter estimator that is unbiased, of finite variance, and achieves the optimal Monte Carlo complexity in the number of unbiased estimators used.
Finally, we address conditional stochastic optimization when the relevant distributions can only be accessed via MCMC rather than exact simulation. Combining Markovian stochastic approximation with a double-randomization unbiased estimation scheme, we construct a gradient estimator that is unbiased with finite second moment, and apply it to model-averaged state-space parameter estimation and high-dimensional portfolio selection on real equity data.
Advisors:
Prof. Ajay Jasra and Prof. Raúl Tempone
Committee:
Prof. Greg Pavliotis, Prof. Diogo Gomes, Prof. Håvard Rue